How to Make a Long Term Care Policy Actually Pay for a Home Aide
Your policy will pay for a home health aide, but it will not pay the agency and it will not pay from day one. Almost all of these policies reimburse you after the fact, which means you pay the invoices first, send them in, and wait. Most also have an elimination period, a stretch of care you fund entirely yourself before any benefit starts.
What actually turns the benefit on?
Needing help with two of the six activities of daily living, or having a severe cognitive impairment. That is the standard trigger in nearly every modern policy, and the expectation is usually that the need will last at least 90 days. The six are bathing, dressing, eating, toileting, transferring and continence.
Two things trip families up here. The first is that housekeeping, laundry, meals, shopping and driving are not on that list. Those are instrumental activities, they are the ones that fail first, and a person can need all of them and still not trigger a benefit. We wrote out the full difference on ADLs and IADLs and why the count matters.
The second is that reminding is not assisting. If your father can bathe himself once somebody tells him to, an assessor may score bathing as independent. Cognitive impairment is the separate door for exactly that situation, so if memory is the real problem, say so plainly in the claim rather than describing the bathing.
What is the elimination period and why does it cost me money?
It is the waiting period at the front of the claim, commonly 30, 90 or 100 days, and you pay for care during all of it. Read how your policy counts those days, because there are two methods and the difference is large.
- Calendar days. The clock runs once you qualify, whether or not anybody came to the house that day. A 90 day period is about three months.
- Days of paid service. Only days an aide actually worked are counted. If you start with three visits a week, a 90 day period takes roughly seven months to satisfy.
If yours counts service days, front loading the schedule gets you through the waiting period sooner. Some policies waive the elimination period for home care entirely, which is worth checking before you assume the worst.
Does the insurer pay me or pay the agency?
You, in most cases. A reimbursement policy pays you back for documented expenses up to a daily or monthly maximum, so the money arrives after you have already paid us. Budget for that gap. A smaller number of policies are indemnity or cash policies, which send a fixed amount once you qualify and do not care what you spend it on, and those are much simpler to live with.
A few insurers will assign a case manager and pay an agency directly. Ask on the first call whether direct billing is available, because nobody volunteers it.
Can I use the policy to pay a family member or someone I hire myself?
Usually not, and this is the single most common reason a claim gets denied. A large share of policies will only reimburse care delivered by a licensed or certified home care agency, and many specifically exclude family members living in the home. A neighbor you pay cash is almost never reimbursable.
Call the insurer before you hire anybody and ask one question in these words: does my policy require a licensed agency, or will it reimburse an independent caregiver? If the answer is agency, hiring privately first means paying out of pocket for care the policy would have covered.
What will the insurer want from us every month?
Proof the visits happened. In practice that means an itemized invoice with the dates, the arrival and departure times, the hours billed and the rate, plus the agency's license information and often a plan of care signed by a nurse or doctor. Many insurers also want a short progress note on what the aide assists with.
Every visit we do is logged in MyCase, our own coordination system, so the times and tasks are recorded as they happen rather than reconstructed at the end of the month. That is the paperwork an adjuster asks for, and it is also how you know the aide came.
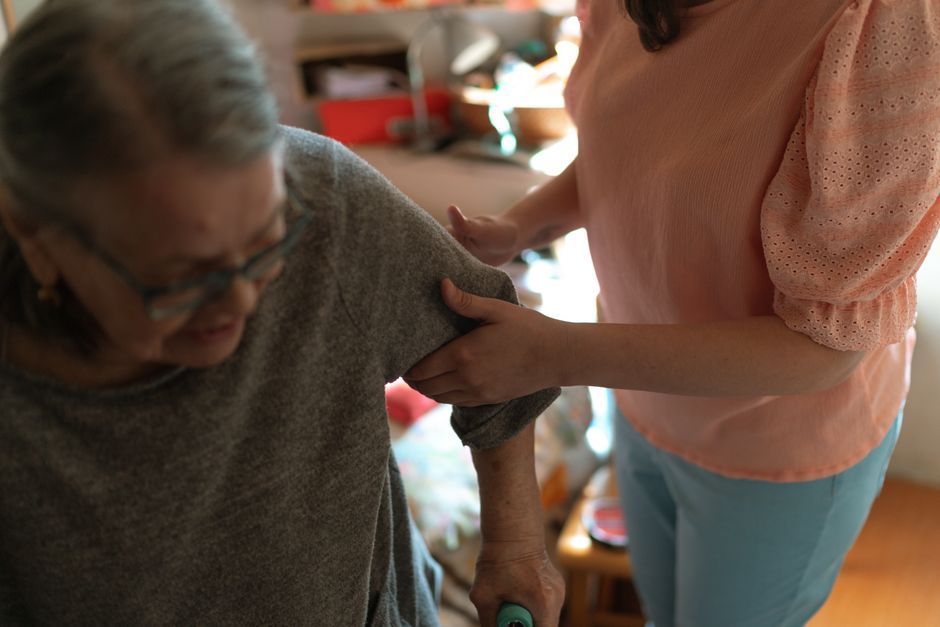
Hands on help with transferring and walking is the kind of assistance a benefit trigger is written around.
How much of the cost will a policy actually cover?
Compare your daily or monthly maximum against the real number of hours you need. Our home health aide care is $45 an hour, from one to eight hours a day, with no minimum contract and no assessment fee. Four hours a day comes to $180 a day. Overnight coverage is $540 for a 12 hour night and around the clock care is $1,080 a day.
If your policy pays a lower daily maximum than the care costs, you are covering the difference, and that is normal. Policies written years ago were priced against years ago rates. Check whether yours has inflation protection, because that one feature decides whether the benefit still means anything.
Also look for the lifetime maximum or benefit pool. Many policies cap the total they will ever pay, so starting at the maximum hours when fewer would do burns the pool faster than it needs to be burned.
My parent's policy is old and only mentions nursing homes. Is it useless?
Possibly, for home care. Policies sold before the mid 1990s were often facility only, and some later ones pay a reduced home care benefit, such as half the nursing home rate. Find the actual policy document rather than relying on memory of what the agent said, and read the section headed home health care or home and community based care. If there is no such section, a hard conversation about where the money comes from is better had now than from a hospital hallway.
What if there is no policy at all?
Three things are worth checking before you resign yourself to writing checks forever.
- Veterans benefits. A veteran or a surviving spouse who qualifies for a VA pension and needs help with daily activities may be eligible for an increased monthly payment known as Aid and Attendance. It goes to the household, not to an agency, so it can fund private aide hours. Start at VA.gov or with the Veterans Service Officer at your city or town hall, and expect the application to take months.
- The medical expense deduction. If you itemize, qualifying medical expenses above 7.5 percent of your adjusted gross income are deductible, and amounts paid for help with activities of daily living can count when the care is part of a plan prescribed by a licensed practitioner. Keep every invoice and ask a tax preparer before you count on a number.
- Your local Aging Services Access Point. If paying privately is simply not possible, the state funded home care program is income based and the ASAP for your town is who decides. Call them before you spend savings you will need later.
Will Medicare cover any of this?
No, not for the kind of help this page is about. Medicare pays for skilled care, meaning a nurse or a therapist, for a limited period when a doctor orders it and the person is homebound. An aide in the house for a few hours a day to help with bathing, dressing and meals is custodial care, and Medicare has never paid for it. Some Medicare Advantage plans now include a small allowance of in home support hours, so if your parent is on an Advantage plan it is worth one phone call to ask.
What is the fastest way to start?
Open the claim and begin the care at the same time. The elimination period cannot start running until care is being delivered, and we can start before the paperwork is finished because there is no minimum contract to sign and no assessment fee. Waiting for an insurer to answer is waiting with no benefit accruing.
One thing to be clear about: our aides are trained, background checked and insured, but they are not nurses and they cannot administer medication. They can be present while a client takes their own, help if something goes wrong, and call for help. If a policy's plan of care calls for nursing, that is a separate service.
Care Remedy serves eastern and central Massachusetts from offices in Woburn, Brockton and Springfield. Call 781-957-8076 and tell us what the policy says. We will tell you what documentation we can provide before you file.
Policy terms vary and nothing here replaces reading your own contract or speaking with your insurer or a tax professional.
Share