Using Life Insurance to Pay for Home Care in Massachusetts
Need help in Massachusetts? Care Remedy provides home health aides at $45 an hour, stair assistance at $200 a visit and wheelchair transportation from $115 each way. Call 781-957-8076 .
Yes, and there are three routes. You can draw an accelerated death benefit from a policy you keep, you can sell the policy outright in a life settlement, or you may already hold a combination policy that was built with a long term care benefit attached. All three trade your beneficiaries' inheritance for money now, which is the real decision underneath the paperwork.
How does an accelerated death benefit work?
You take an advance on your own death benefit while you are still living. Some policies include the feature at little or no cost, others charge extra for the rider. According to the federal Administration for Community Living, payouts are commonly capped at about half the death benefit, though some policies allow the full amount. Whatever you draw reduces what your beneficiaries receive later, dollar for dollar.
How much will it actually pay toward care at home?
Less than it pays toward a nursing home. The Administration for Community Living describes a common structure: a monthly benefit of roughly 2 percent of the policy face value for nursing home care, and often half that for care at home. On a $200,000 policy that works out to about $4,000 a month in a facility and about $2,000 a month at home. Read your own policy before you count on either figure, because that split is a pattern in the market and not a rule, and some policies do not cover home care at all.
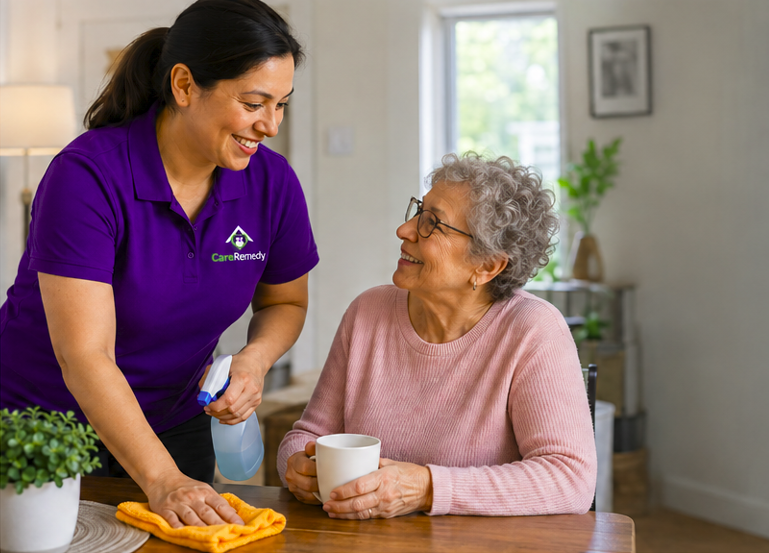
Home health aide care covers bathing, dressing, meals, light housekeeping and companionship. It is priced by the hour, which makes it easy to match against a fixed monthly benefit.
How many hours of care does $2,000 a month buy?
At our published rate of $45 an hour, about 44 hours a month. For scale, on a 30 day month, 3 hours twice weekly runs about $1,170, 2 hours a day about $2,730, 3 hours a day about $4,095, 4 hours a day about $5,460, 6 hours a day about $8,200 and 8 hours a day about $10,900. An accelerated benefit sized around nursing home math usually will not carry daily home care by itself. What it does carry well is a morning shift, a bridge while you arrange something more permanent, or the gap between barely managing and managing.
The full hourly and monthly breakdown is here: what home care costs per hour and per month in Massachusetts.
What is a life settlement, and who qualifies?
You sell the policy to a third party for more than its surrender value and less than its death benefit, then spend the proceeds on whatever you choose, including care. The Administration for Community Living notes it is generally available to women 74 and older and men 70 and older, and that no health screening is required. Your heirs receive little or nothing from that policy afterward.
What is a viatical settlement, and how is it different?
A viatical settlement is a sale open only to someone terminally ill with a life expectancy of two years or less. The buyer pays a percentage of the death benefit scaled to life expectancy, then takes over ownership, the beneficiary position and the premium payments. Under the model guidelines the industry follows, that percentage runs from about 80 percent at a life expectancy of one to six months down to about 50 percent beyond two years. Viatical companies approve fewer than half of the people who apply.
Is the money taxed?
It depends which route you take. Accelerated death benefits are generally received tax free. Life settlement proceeds may be taxable. Viatical proceeds are tax free if you are terminally ill with a life expectancy of two years or less, or chronically ill, and the company is licensed in the states where it does business. Run your own numbers past an accountant before you sign anything, not after the money has moved.
Will this affect MassHealth eligibility?
It can, and this is the part people get wrong. Cash sitting in a bank account is a countable asset in a way that a death benefit is not, and the Administration for Community Living warns plainly that accelerated death benefits may affect Medicaid eligibility. MassHealth is Medicaid in Massachusetts. If applying for MassHealth long term care coverage is anywhere in the plan, even a few years out, talk to an elder law attorney before you draw down or sell a policy. Both the timing and the amount matter.
What should I check before I touch the policy?
- Whether the policy already includes an accelerated death benefit, and whether it costs extra
- Whether it pays for care at home or only in a facility
- The maximum you can draw, and over what period
- What triggers the benefit, since many require certification that you need help with daily activities
- What death benefit would remain for your beneficiaries afterward
- Whether premiums continue during the payout, and who is responsible for paying them
- Whether inflation protection exists, because most accelerated benefits have none
Is there a cheaper place to look first?
Yes, and you should exhaust these before you touch a death benefit. If a long term care policy exists, it pays without costing your heirs anything, and getting a long term care policy to actually pay for a home aide is its own process worth learning. An HSA or FSA can cover qualifying care with money you already set aside. Veterans and surviving spouses may qualify for VA Aid and Attendance. Your local Council on Aging and your regional Aging Services Access Point can tell you what subsidized hours you may already be entitled to. Spend other sources first, then the policy.
What does the certification requirement usually mean?
Most policies that pay for care require a licensed clinician to certify that you need substantial help with a set number of activities of daily living, or that you have a cognitive impairment requiring supervision. The common threshold is help with two of six activities. That certification is a clinical judgment and it comes from your doctor, not from an agency and not from an aide.
Care Remedy provides home health aide care across Massachusetts, 1 to 8 hours a day, with no minimum contract, no assessment fee and no four hour minimum per visit, from offices in Woburn, Springfield and Brockton. Call 781 957 8076 or email info@careremedyinc.com.
Our aides are trained, background checked and insured, and they are not nurses. They do not administer medication, including insulin, do not change dressings, and do not make clinical judgments. Skilled nursing is a separate service, priced separately.
This page is general information, not tax, legal or financial advice. Confirm the tax treatment and the MassHealth consequences with your own accountant, attorney or financial advisor before you change or sell a life insurance policy.
Share